The Day in Numbers
- US 10-year Treasury yield: 5.24% — held near recent highs as investors weighed further rate increases against a slowing labor market.
- S&P 500: 7,666.45 — rose 0.19%, a modest gain that concealed sharper regional and sectoral divergences.
- Nasdaq: 26,871.60 — added 0.04% as AI enthusiasm barely offset pressure from rates and geopolitical risk.
- FTSE 100: 10,428.27 — fell 1.68% as London equities absorbed another bout of bond-market stress.
- Crude oil: $91.77 — declined 1.18%, though the Middle East escalation kept supply risk firmly in the inflation debate.
- Gold: $4,209.60 — gained 0.17% as slightly easier Treasury yields restored some demand for protection.
- 30-year mortgage rate: Nearly 7.3% — posted its largest four-year jump, extending the bond market’s pressure into household finance.
Iran Raises the Price of Optionality
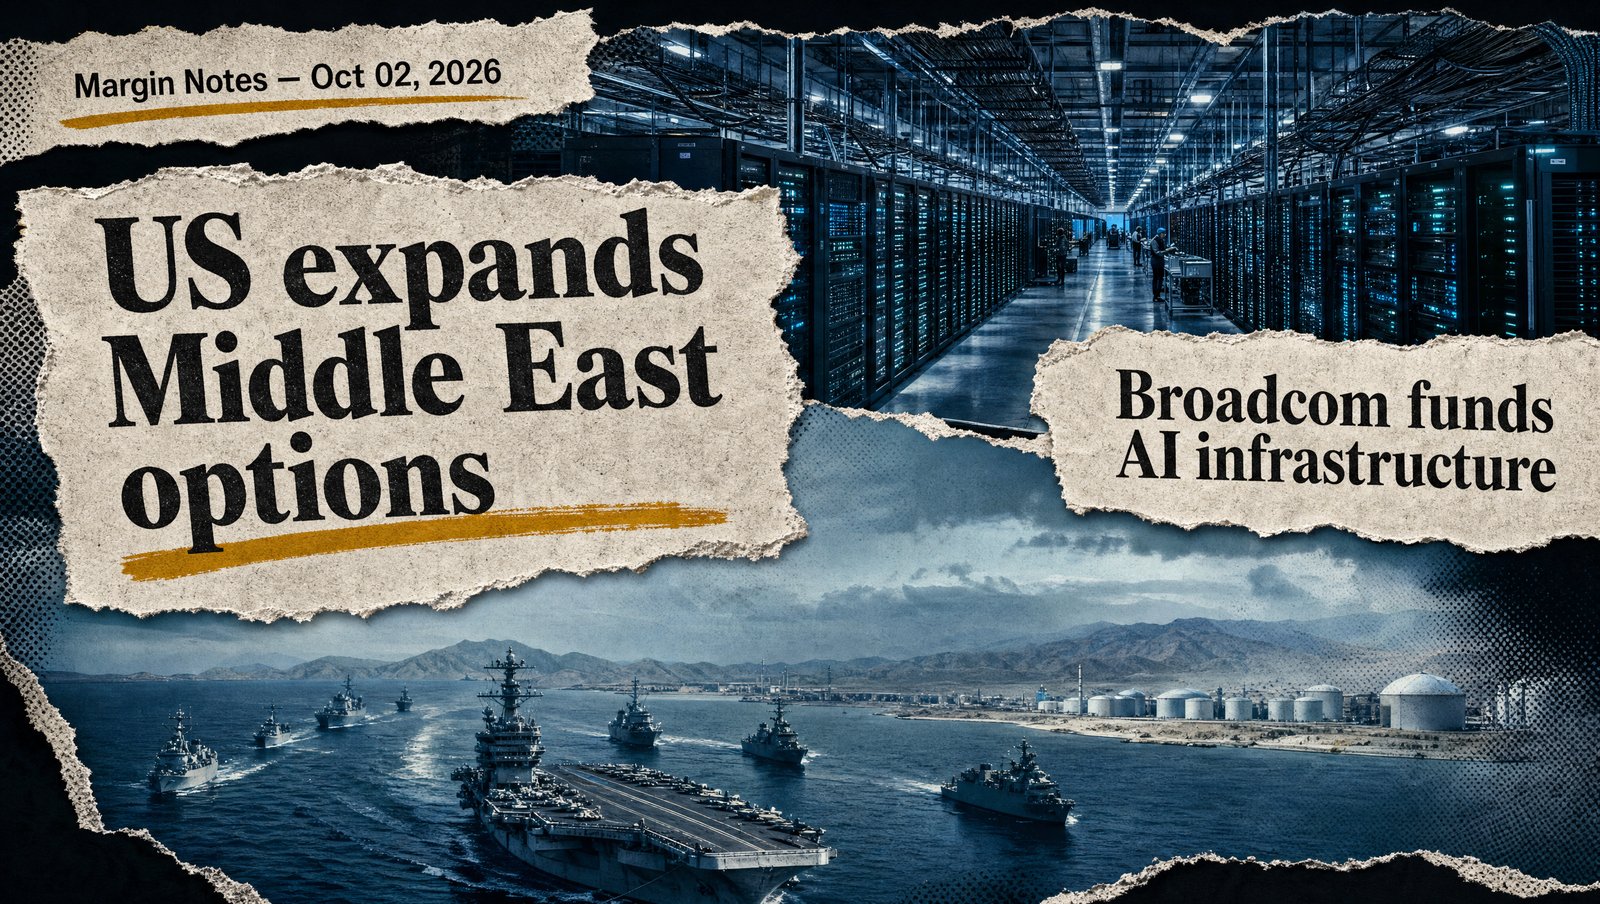
The United States added a carrier and 10,000 troops to the Middle East as commanders prepared for a possible escalation with Iran. The US military expanded its regional options as the conflict widened, and markets responded with the odd restraint that often accompanies a well-telegraphed danger: crude fell 1.18% to $91.77, while gold rose 0.17% to $4,209.60.
That does not make the development benign. Oil is still high enough to complicate inflation, and the possibility of disruption matters more than the direction of one settlement price. The refining system is already carrying strain, while a broader conflict could turn transport, insurance, and fuel costs into a second wave of inflation. Gold recovered as lower yields revived its insurance appeal, but the modest move says investors are hedging rather than fleeing.
The distinction matters for equities. The S&P 500 gained 0.19%, yet London’s FTSE 100 fell 1.68% as bond volatility and regional fiscal concerns collided. Markets can absorb a geopolitical headline when they believe the damage is contained. They become less accommodating when military uncertainty arrives alongside expensive money and fragile sovereign debt.
The US Fed Keeps October Uncomfortable
The US 10-year Treasury yield held at 5.24% even as buyers returned to government bonds, leaving the market to reconcile a rebound in prices with a still-hostile policy message. Dallas Fed President Lorie Logan argued that more rate increases may still be needed, while US Fed Vice Chair Philip Jefferson said inflation remained too high and required more time to assess. The committee may lean against an October hike, but “not yet” is not the same thing as “never.”
Friday’s employment report therefore carries more weight than its usual monthly cameo. Forecasts call for 84,000 new jobs, down from 162,000 in August, with unemployment expected to remain at 4.1% and average hourly earnings projected to rise 0.3% month over month. Treasury yields rebounded before the labor data that could decide the next policy argument. A soft payroll number could support bonds and growth stocks; a firm wage reading would keep the US Fed’s inflation concern alive.
The cost is already visible outside trading screens. The 30-year mortgage rate jumped to nearly 7.3%, its largest increase in four years, while financial stocks are struggling to hold important technical levels. The bond market is no longer merely setting the valuation for long-duration assets. It is setting the monthly payment on a house, which gives the abstract concept of term premium a rather more personal address.
AI Capital Finds a More Demanding Buyer
Broadcom began assembling a $60 billion financing package for chips destined for Anthropic, putting a very large figure behind the next phase of the AI buildout. Broadcom is turning AI demand into a $60 billion infrastructure commitment, and that helps explain why the Nasdaq managed a 0.04% gain despite a 5.24% 10-year yield. Investors still want exposure to computing capacity; they are simply asking who pays for it and when the revenue arrives.
The answer is becoming more infrastructure-heavy. Nvidia-backed Firmus priced an Australian IPO at A$11 a share, while HPE reached a record high on networking demand and AMD Helios orders. These are not software dreams floating above the economy. They are data centers, power systems, networking equipment, and financing structures, all of which must survive rates that no longer politely sit in the background.
Crypto is following the same institutional logic, though with more regulatory paperwork and fewer hard hats. The US Securities and Exchange Commission proposed custody rules for investment advisers and funds, while Citigroup lifted its 12-month Bitcoin target to $113,000 as ETF inflows resumed. The US SEC is building custody rules where legislation failed to arrive. That may improve the market’s plumbing even as Bitcoin remains trapped in the $82,000-to-$85,000 range. Capital is still willing to fund the future. It just wants the future properly documented.
Elsewhere
- Firmus priced its Nvidia-backed IPO at A$11 a share, giving investors a public-market test of demand for data-center infrastructure.
- Global credit markets began showing strain in jumbo deals as investors became less willing to absorb large borrowings without extra compensation.
- French investors moved toward the exits while unions prepared budget strikes, widening the country’s fiscal and political risk premium.
- The IMF approved El Salvador funding after granting a Bitcoin-related waiver, allowing the country to retain its digital-asset strategy while accessing official support.
- A $3.8 million exploit hit NEAR Intents, another reminder that institutional ambition does not make cross-chain code any less breakable.
- EU regulators questioned Binance’s reliance on reverse solicitation, putting fresh pressure on the exchange’s ability to serve European users.
- AI tools were suspected in a Shinhan Bank hack in South Korea, adding cybersecurity risk to the list of costs attached to faster automation.